Georgia’s 25/50/25 Rule Leaves a Gap for Seriously Injured Drivers
Key Takeaways: Georgia’s minimum car insurance is 25/50/25: $25,000 for one person’s injuries, $50,000 per crash, and $25,000 for property damage. A serious injury often costs far more. When the at-fault driver’s coverage won’t pay for your losses, O.C.G.A. § 33-7-11 may treat that driver’s vehicle as "uninsured," so you may be able to claim on your own uninsured motorist (UM) coverage. Your policy generally includes UM coverage unless you turned it down in writing. The default "added-on" type generally pays on top of the at-fault driver’s limits, while "reduced-by" coverage generally pays only the difference between those limits and your UM limits. You may also be able to pursue the at-fault driver personally for the rest of a judgment. Paying the statutory amounts lets the driver get their license back, but it doesn’t cancel the larger debt. Don’t accept a quick policy-limits settlement or sign a release before you understand your UM rights and future medical needs.
If the at-fault driver’s $25,000 policy can’t cover your losses, you may still have other ways to recover. The usual places to look are your own uninsured motorist (UM) coverage and a direct claim against the at-fault driver for the rest of a judgment. Georgia treats an underinsured vehicle as "uninsured" under its uninsured motorist statute. A serious injury can produce hospital bills, surgery costs, and lost income that pass $25,000 within weeks. How much you recover often depends on choices you made on your own auto policy, sometimes years before the crash.
If you were hurt in a crash in Dalton or elsewhere in Georgia and the other driver’s policy limits look too low, you can talk with a legal team that represents injured people. The Law Offices of Darwin F. Johnson represents injured drivers, passengers, and pedestrians in claims where the insurance doesn’t match the harm. Call 404-521-2667 or contact us now to talk about your situation.
What Georgia State Minimum Car Insurance Actually Covers
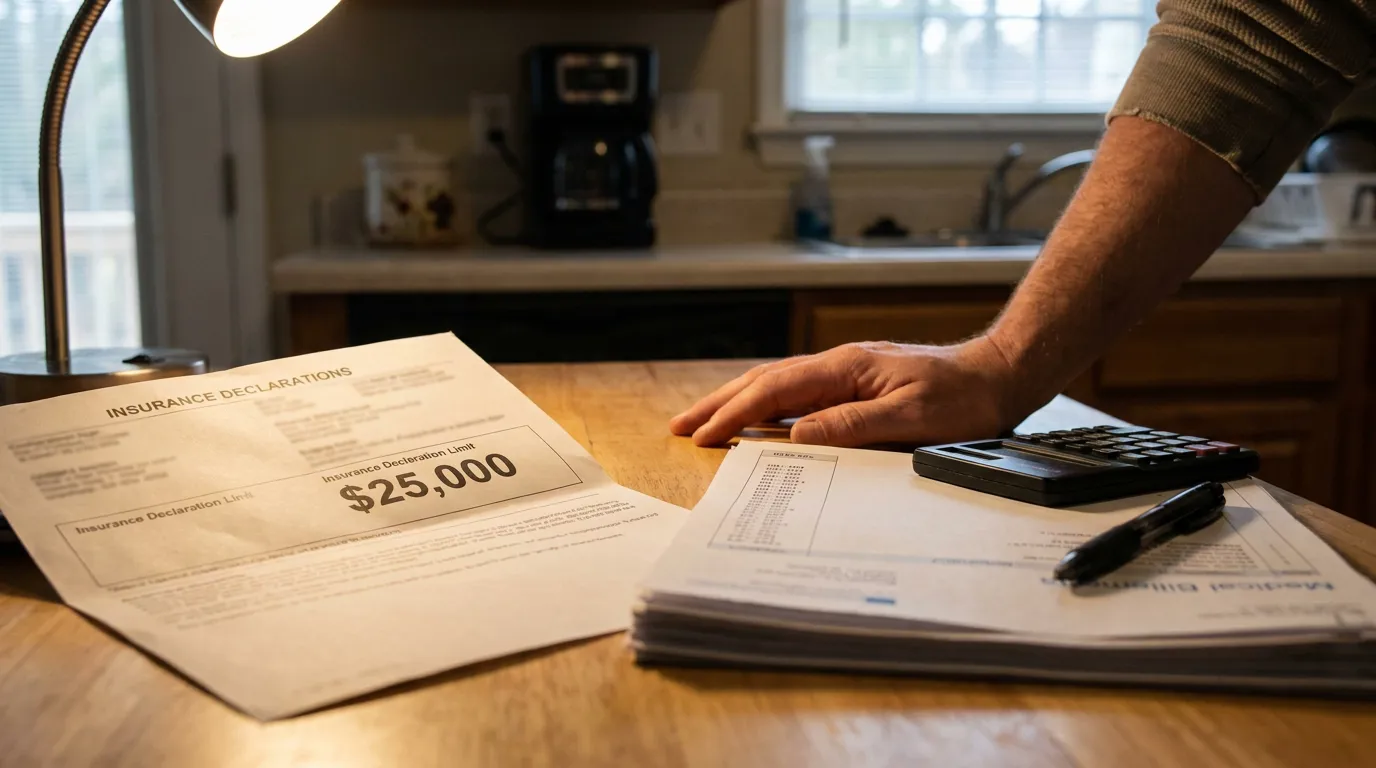
Georgia state minimum car insurance is usually described as 25/50/25 coverage. That means $25,000 for the injury or death of one person, $50,000 for two or more people in one crash, and $25,000 for property damage. These minimums come from Georgia statutes, including O.C.G.A. § 33-7-11 and § 33-34-4. Related rules appear in the official Georgia Administrative Code, Chapter 115-4, maintained by the Georgia Secretary of State.
The same numbers show up in the Motor Vehicle Safety Responsibility Act. Under O.C.G.A. § 40-9-62(b)(1)-(3), for accidents on or after January 1, 2001, a judgment against an at-fault driver counts as satisfied for license reinstatement once the driver pays $25,000 for one person’s injury or death, $50,000 for two or more people, and $25,000 for property damage.
Why $25,000 Rarely Matches the Real Cost of an Injury
The $25,000 bodily injury limit is the legal minimum. It isn’t a measure of what an injury is worth. One emergency room visit with imaging can use up a large share of it. Traumatic brain injuries, spinal cord damage, and fractures that need surgery can lead to years of treatment, lost earning capacity, and pain and suffering. When damages pass the policy, you may have to look to other sources of coverage.
How Negligence Shapes Your Injury Claim
Injury claims against an at-fault driver in Georgia generally rest on negligence. As Georgia Legal Aid explains in its overview of negligence claims in Georgia, you generally have to prove duty, breach, causation, and damages. Damages reflect what you actually lost, not how much insurance the other driver bought. Under Georgia’s modified comparative fault rule, O.C.G.A. § 51-12-33, your share of fault reduces your recovery, and you can’t recover anything if you are 50% or more at fault.
Proving those elements often takes more than a police report. In serious cases, you may need medical records, treating doctor testimony, crash reconstruction, and wage records to show the claim’s full value. That evidence also matters for your UM claim, because your own insurer may fight the amount of your losses just as hard as the other driver’s carrier would.
Underinsured Driver Georgia Rules: How UM Coverage Fills the Gap
Georgia generally treats an underinsured driver as an uninsured motorist under O.C.G.A. § 33-7-11. Under § 33-7-11(b)(1)(D)(ii), a vehicle that has liability insurance can still count as "uninsured." With added-on coverage, this applies when the available liability coverage is less than your total damages. With reduced-by coverage, it applies when the liability coverage is less than your own UM limits.
Georgia law generally requires every auto liability policy to include UM coverage. O.C.G.A. § 33-7-11(a)(1) says no one may issue an auto liability policy in Georgia unless it includes UM coverage for bodily injury, death, or property damage caused by uninsured or underinsured drivers. Under § 33-7-11(a)(1)(A), UM limits for vehicles mainly kept or used in Georgia must be at least 25/50/25 unless the insured rejects the coverage in writing.
When Coverage Is Automatic and When It Was Rejected
Your policy generally includes UM coverage unless you rejected it in writing. Under O.C.G.A. § 33-7-11(a)(3), without a written rejection, the policy generally includes UM coverage equal to its liability limits. Under § 33-7-11(a)(1)(B), you can also choose lower limits in writing, but not below the statutory minimums. Check your declarations page to see what you actually chose.
Other Situations That Count as "Uninsured"
A vehicle can also count as uninsured when its insurer won’t or can’t pay. Under O.C.G.A. § 33-7-11(b)(1)(D)(iii)-(iv), this includes cases where the liability insurer has legally denied coverage or is insolvent. If an insolvent insurer pays part of the claim, the vehicle generally counts as uninsured only for the difference between that payment and the UM limits.
💡 Pro Tip: Ask your own insurer for a certified copy of your full policy, including any signed UM rejection or selection forms. The signed paperwork, not your memory, generally controls which coverage applies.
Added-On vs. Reduced-By Coverage: The Choice That Changes Your Recovery
Which type of UM coverage you have can change your available compensation by tens of thousands of dollars. For policies issued or renewed on or after January 1, 2009, Georgia’s default is "added-on" (excess) coverage. Under O.C.G.A. § 33-7-11(b)(1)(D)(ii)(II)-(III), you can turn it down in writing and choose "reduced-by" coverage instead. Under § 33-7-11(a)(3), you can also reject UM entirely in writing.
| Coverage Type | How It Works | Example: $25,000 Liability + $100,000 UM |
|---|---|---|
| Added-On (default) | UM generally pays on top of the at-fault driver’s liability limits, up to the full UM limits | Potentially up to $125,000 available |
| Reduced-By | UM generally pays only the difference between the at-fault driver’s liability coverage and your UM limits | Potentially up to $100,000 available |
| Rejected | No UM benefits | Generally only $25,000 from the at-fault policy |
Even added-on coverage has limits. Under O.C.G.A. § 33-7-11(b)(1)(D)(ii)(I), UM coverage doesn’t repeat what the liability policy paid, and your total recovery from both sources can’t exceed your total economic and noneconomic losses. Some drivers may also reach coverage on more than one policy. You can read more in our explanation of UM stacking in Georgia.
Can You Pursue the At-Fault Driver Personally?
In many cases, yes. The rest of a judgment generally doesn’t disappear just because the insurance ran out. O.C.G.A. § 40-9-62(b) says the "deemed satisfied" rule applies only for purposes of the Motor Vehicle Safety Responsibility Act chapter. Paying the statutory amounts lets the driver get their license back, but it doesn’t cancel the rest of a larger civil judgment. A limited release under O.C.G.A. § 33-24-41.1, or a bankruptcy discharge, may limit personal collection.
Collecting the rest is a separate, practical question. Many drivers with only Georgia minimum car insurance have few assets, so a valid judgment may be hard to collect. Consider these points:
- Whether the at-fault driver has assets, other insurance, or an umbrella policy
- Whether an employer or vehicle owner may share liability
- Whether your own UM coverage, including stacked policies, is available
- Whether the cost and time of a lawsuit make sense given what you can collect
Common Mistakes That Can Shrink Car Accident Compensation
Accepting a quick policy-limits payment without protecting your UM rights can cause serious problems. If you file suit, you generally must serve your own UM carrier under O.C.G.A. § 33-7-11(d), and settlements often need a limited release under § 33-24-41.1 to keep the UM claim alive. Missing deadlines, including Georgia’s general two-year statute of limitations for personal injury, or signing a general release can end your UM claim. Get advice before signing any release.
Another common mistake is underestimating future damages. A claim that seems worth $25,000 early on can grow much larger once doctors find a need for surgery or long-term care. Settling before your medical picture is clear may leave you without money for later treatment.
💡 Pro Tip: Keep a daily journal of pain levels, missed activities, and work limits. Notes written at the time can help support noneconomic damages that medical bills alone don’t show.
Frequently Asked Questions
-
Is $25,000 the most I can recover after a Georgia car accident?
Not necessarily. $25,000 is the minimum per-person liability limit, not a cap on damages. You may be able to recover more through your own UM coverage or by pursuing the at-fault driver personally.
-
Do I have UM coverage if I never asked for it?
Possibly. Under O.C.G.A. § 33-7-11(a)(3), your policy generally includes UM coverage equal to your liability limits unless you rejected it or selected lower limits in writing.
-
Does underinsured coverage exist separately in Georgia?
No. Georgia handles underinsured drivers under its uninsured motorist statute, O.C.G.A. § 33-7-11(b)(1)(D)(ii), rather than through a separate coverage type.
-
What if the other driver’s insurer goes bankrupt?
Under O.C.G.A. § 33-7-11(b)(1)(D)(iv), a vehicle insured by an insolvent carrier may count as uninsured. If the insurer made a partial payment, the vehicle generally counts as uninsured only for the difference between that payment and your UM limits.
-
Does the at-fault driver still owe me after paying their policy limits?
They may. Under O.C.G.A. § 40-9-62(b), the "deemed satisfied" rule applies only to license reinstatement and generally doesn’t erase the rest of a larger judgment. A limited release or bankruptcy can affect this.
Protecting Your Recovery When Coverage Falls Short
Georgia state minimum car insurance often isn’t enough for people hurt in serious crashes, but the law may offer more than one way to recover. Your own UM coverage, the difference between added-on and reduced-by coverage, possible stacking, and a direct claim against the at-fault driver can all affect how much you recover. Every case depends on its own policy language, evidence, and facts.
If the at-fault driver’s insurance won’t cover your injuries, an experienced Georgia car accident lawyer can review every available source of coverage with you. The Law Offices of Darwin F. Johnson prepares injury claims as if they will go to trial and works to get injured clients a full recovery. Call 404-521-2667 or schedule your consultation today.
Disclaimer: This content is for informational purposes only and is not legal advice. Every case is unique, and results may vary. Consult an attorney about your specific circumstances.
Credibility Records Referenced: None